

Claims & Fine Print
Year-End Coverage Check: Is Your Policy Still Doing Its Job?
Life changes fast. Here is a simple year-end checklist to make sure your policy still fits your life.
Edwin Badu·
Nov 15, 2026
Expert advice, tips, and guides to help you make smart life insurance decisions for your family
Life changes fast. Here is a simple year-end checklist to make sure your policy still fits your life.

Your photos and online accounts need a plan too. Here is how to handle your digital life alongside your life insurance.

Ever think about what happens if your beneficiaries pass away before you? It could lead to probate. Here is how to make sure that doesn't happen.
An outdated beneficiary form can send your money to the wrong person. Here are the life events that should prompt a quick update.
Disputes over payouts can destroy families. Here is how to make sure your wishes are clear so there's no confusion later.
A denied claim feels like a gut punch, but it's not always the end of the road. Here is how you can fight back.
Just because you got approved doesn't mean your coverage is untouchable. Here’s what can void a policy and how to keep yours safe.
Nearly every life insurance policy has a suicide clause. Here is what it actually says, how long it lasts, and what it means for families.
In the first two years of a policy, insurers can take a closer look at claims. Here is what the contestability period means for you.
These two Latin terms decide who gets a beneficiary's share if they pass before you. Here is what per stirpes and per capita really mean.
It seems natural to name your kids as beneficiaries, but doing it directly can backfire. Here is the mistake to avoid and the better way.
Usually, you'd just name a person to get your life insurance money. But sometimes, a trust is the better way to make sure the money is used the way you want.
It sounds a bit strange, but some permanent life insurance policies can actually help fund your retirement. Here is the reality check.
Need-based benefits like Medicaid and SSI are strict. Certain life insurance policies can accidentally hurt your eligibility, so here is how to handle it.
Going through bankruptcy doesn't automatically mean you lose your life insurance policy. It just depends on what kind of policy you have and where you live.
Can creditors come after your life insurance? Often not, but it depends on your state and how things are set up. Here is what to know.
If you have a policy you no longer need, you may be able to sell it for more than its cash value. Here is how life settlements work.
One of life insurance's best features is skipping probate. Here is how that works and the mistakes that can accidentally drag it back in.
A big estate tax bill can force a fire sale of family assets. Here is how life insurance provides the cash to pay it and protect your legacy.
For larger estates, an ILIT can save a fortune in estate taxes. Here is what an irrevocable life insurance trust is and how it works.
Life insurance does more than replace income. Here is how it fits into a smart estate plan to protect and provide for the people you love.
Certain whole life policies pay yearly dividends. Here is what they are, where they come from, and the best ways to put them to work.
Want to switch to a better policy without triggering taxes on your gains? A 1035 exchange can help. Here is how it works.
Permanent life insurance isn't just about the death benefit. There is a 'cash value' account inside, but it is not a savings account. Here is how it works.
When an insurance policy pays out, you have choices. Do you want it all at once or spread out over time? Here is the breakdown.
It is a total mistake to name a person with special needs as a direct life insurance beneficiary. Here is how to do it properly with a trust.
Firefighters, police, and EMTs put their lives on the line for us. Here is how to make sure your family is covered correctly.
Long hours and time on the road do not have to mean expensive life insurance. Here is how truck drivers can find affordable, solid coverage.
School coverage is a nice perk, but it is rarely enough for a teacher's family. Here is how educators can get the protection they really need.
Healthcare workers care for everyone else. Here is how nurses and medical staff can make sure their own families are protected with the right policy.
Blended families need extra care with life insurance to treat everyone fairly. Here is how to protect your spouse and all your children.
You don't need a marriage certificate to look out for each other. Here is the smart way for unmarried couples to handle life insurance.
Just arrived in the US on a visa? Don't assume you can't get life insurance yet. Here is how to navigate the process.
If you've got a green card, you're in luck: you have pretty much the same life insurance options as a US citizen. Here is the breakdown.
Expecting a baby? You can absolutely get life insurance. Here’s a look at how the timing of your application might sway your premiums.
Between living longer and handling the heavy lifting of caregiving, life insurance hits differently for women. Here is what you need to know.
Think you can't get life insurance after 80? You can. Here are the options left for you and how to pick the right one.
Over 70 and think you're past the point of getting life insurance? Think again. Here are the options that actually work for your stage of life.
Turning 65 doesn't mean you're out of luck for life insurance. Here's the deal on your options and how to pick the one that actually works for you.
When you work for yourself, life insurance protects more than your family. It can protect your business and your obligations too. Here is how.
No employer benefits means no built-in life insurance. Here is why gig workers and freelancers need their own policy and how to pick one.
Worried about funeral costs or debts when a parent passes? You can buy life insurance on your aging parents. Here is how to do it the right way.
Getting a better rate class means you pay less for life insurance, plain and simple. Here is how you can boost your odds of getting a better price.
The MIB is a secret database that insurance companies use to keep everything consistent. Here is what they track, why they do it, and how to check your own records.
When you apply for life insurance, the company can pull your prescription records. Here is exactly what they see and why you should just be honest from the start.
If your life insurance price came back higher than you thought, you might be looking at a table rating. Here is the breakdown of why they happen and how you might be able to fix them.
Bariatric surgery can really turn your health around and eventually help you score better life insurance rates. Here is what insurers care about and how to time your application right.
Cannabis use is more accepted than ever, and life insurers have adapted. Here is how marijuana use affects your application in 2026 and how to get a good rate.
A DUI on your record can raise your life insurance rate, but the effect usually fades with time. Here is how insurers see it and what you can do.
A heart attack in your past does not end your chances of coverage. Here is how insurers look at it and how to put your best foot forward.
GLP-1 drugs like Ozempic are everywhere now. Here is how they affect life insurance underwriting and the smart way to handle your application.
Don't let high cholesterol scare you off from applying for life insurance. It’s usually very manageable. Here’s what insurers look at and how you can still score a good rate.
Sleep apnea is super common, and insurance companies know it. Here is the deal on how it affects your rates and why staying on top of treatment is your best bet.
Insurers check your height and weight to figure out your BMI. Here is how that number messes with your premium and a few ways to land in a better rate bracket.
High blood pressure is one of those common health things people stress over, but it’s actually pretty easy to handle. Here’s how it affects your premiums and what you can do to get a fair price.
If you have heart disease, insurance companies are definitely going to ask some questions. But it doesn't mean you're out of luck. Here is what to expect and how to handle it.
Just because you had cancer doesn't mean you can't get coverage. Here is how insurance companies look at survivors and how to get a fair rate.
You might have heard people bragging about being their own bank with life insurance. It sounds cool, but here is the real story on whether it's a good move or just hype.
Annuities and life insurance sound kind of similar, but they do totally different things. One is for if you die too early, the other is for if you live too long. Here’s the scoop.
Quitting your job usually means losing your work-provided life insurance. Here is why that’s a problem and how to fix it.
Not all insurance apps are the same. Some take weeks, some take minutes. Here’s the difference between the three main types and what you should aim for.
AD&D is cheap, but it’s got a big catch: it only covers accidents. Here’s why you shouldn't swap it for real life insurance.
With decreasing term, your payout shrinks over time to follow your mortgage. It sounds good, but here’s why plain old level term is usually the better deal.
Survivorship policies cover two people and only pay out when the second person dies. Here is how it works and why it's a popular choice for estate planning.
Hybrid policies combine life insurance with long-term care, so your money isn't wasted. Here is the breakdown on how they work and who they are for.
Return-of-premium term promises your money back if you outlive the policy. It sounds like a winner, but the math is tricky. Here is the truth.
Don't want to mess with cash value accounts? Guaranteed universal life gives you lifelong coverage for a fixed price. Here's the deal.
VUL is complicated. You're investing your cash value, which means real market gains and real losses. Here is who should (and shouldn't) consider this.
IULs get sold with some pretty big promises about winning on the market without losing. We're cutting through the marketing talk to show you the real deal.
Universal life is permanent insurance, but with flexible payments. It sounds great, but there's a catch you need to see. Here is the plain-English breakdown.
Final expense insurance is just a small policy to cover funeral bills. Let's look at how it works, what it costs, and if it's the right choice for you.
It's a fair question: what happens if your life insurer disappears in 30 years? Every state has a safety net called a guaranty association. Here is how that works.
Maybe you found a better rate or your health is better now. Replacing a policy can be smart, but it can also go south if you aren't careful. Here is how to know when to switch and how to do it without any gaps.
You bought a house and now the junk mail for mortgage protection is piling up. Here is how that compares to standard term life insurance and why most people are better off with the latter.
You're trusting an insurance company to pay out years or even decades down the road. Financial strength ratings show you who can actually follow through. Here's how to make sense of them.
Did you buy life insurance years ago? It might not fit your life anymore. Here is how to give it a quick check-up.
Scammers are everywhere. Learn the red flags so you don't get taken.
It happens a lot: family members don't know a policy exists. Here is how to hunt it down.
Don't just listen to the sales pitch. Run through this checklist so you know exactly what you're buying.
Most agents are honest, but a few warning signs should make you pause. Here are 7 red flags to watch for before you sign any life insurance policy.
A 10, 20, or 30 year term? The right length is the one that lasts as long as the people who depend on you. Here is how to choose without overpaying.
The first month after losing someone is overwhelming. This is a practical, step-by-step guide to the financial and administrative tasks that need attention.
These common myths keep families from getting the coverage they need. Let us set the record straight with real numbers and real facts.
$500,000 today will not buy $500,000 worth of groceries in 2046. Here is how inflation affects your coverage and what you can do about it.
Yeah, the medical exam is annoying, but it's not actually that scary. It's quick, free, and we can help you get ready for it.
Freaking out about your life insurance because you're moving? Don't worry. Your policy doesn't just evaporate. Here's what you need to do.
Most people just buy one big policy and forget about it. But laddering—buying a few smaller policies instead—can save you serious cash while still keeping your family safe. Here's the deal.
You paid off the mortgage and cleared your loans. Great work. But does that mean you can cancel your life insurance? Not necessarily.
Working a dangerous job doesn't mean you're uninsurable. It just means you need to be a little smarter about where you apply.
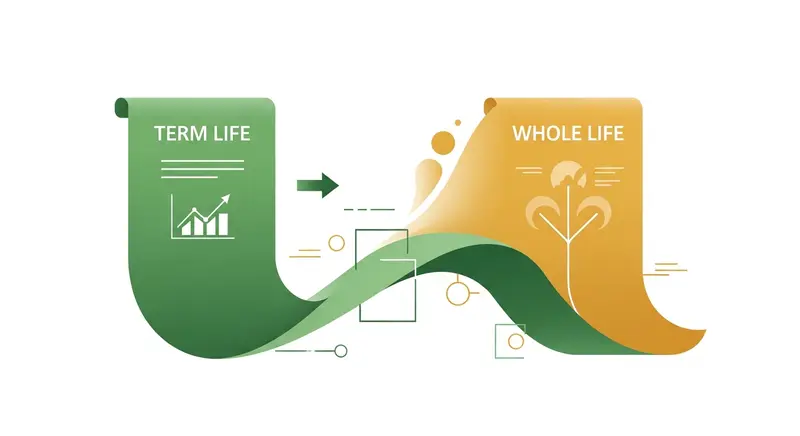
You might have an option to switch your term policy to whole life without a doctor's exam. It is a powerful safety net, but it isn't always the right move.
You bought life insurance, shoved the paperwork in a drawer, and never looked back. We've all done it. But you should probably know what that contract actually says.
If you own a business, life insurance does double duty. It protects your family and your company. Here is how key person coverage, buy-sell agreements, and business continuation work.
Most people do not know their life insurance can pay out while they are still alive. Here is how accelerated death benefits work and why they matter.
Just got married? Here is how to figure out life insurance as a couple, whether you need one policy or two, and how much coverage makes sense.
Whole life insurance lets you borrow against your cash value. But there are risks most people do not understand. Here is how policy loans actually work.
Military families have unique life insurance needs. Here is how SGLI, VGLI, and private coverage compare, and what to do when you leave the service.
Cannot get approved for traditional life insurance? Guaranteed issue exists for a reason. Here is what it costs, how it works, and whether it is right for you.
Not every agent has your best interest at heart. Here is what some agents leave out and what you should know before buying.
Turning 50 doesn't mean you've missed the boat on life insurance. Things work a bit differently now, so here’s the scoop on how to handle it.
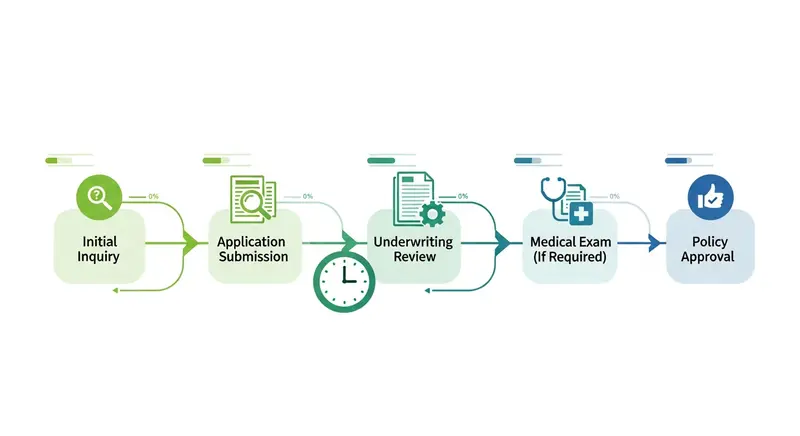
Wondering how long the life insurance process takes? Here is the real timeline from application to approval, with no sugarcoating.
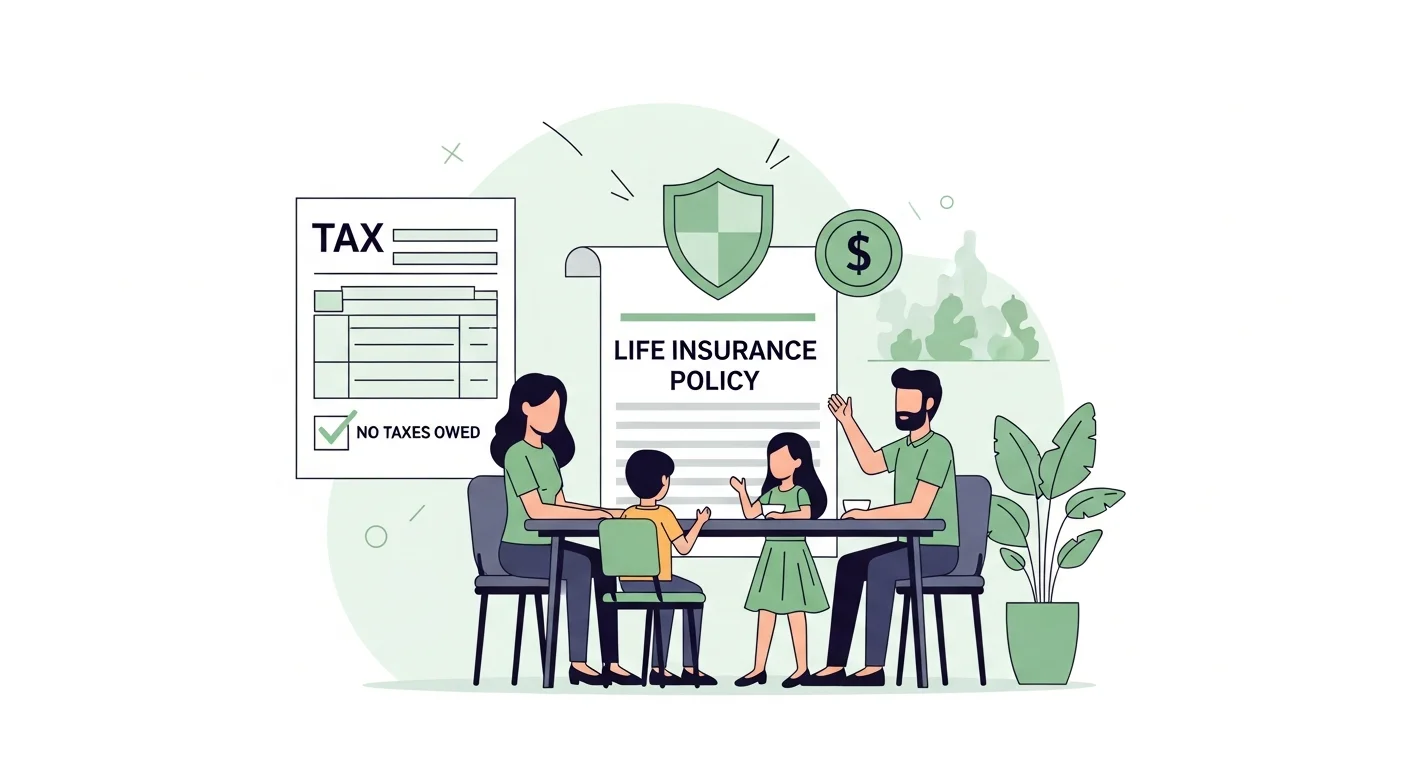
The tax rules around life insurance are simpler than you think. Here is what is taxable, what is not, and the situations where taxes might apply.
Diabetes does not mean you can not get life insurance. Here is what carriers look for, what you will actually pay, and how to get the best rate for your situation.
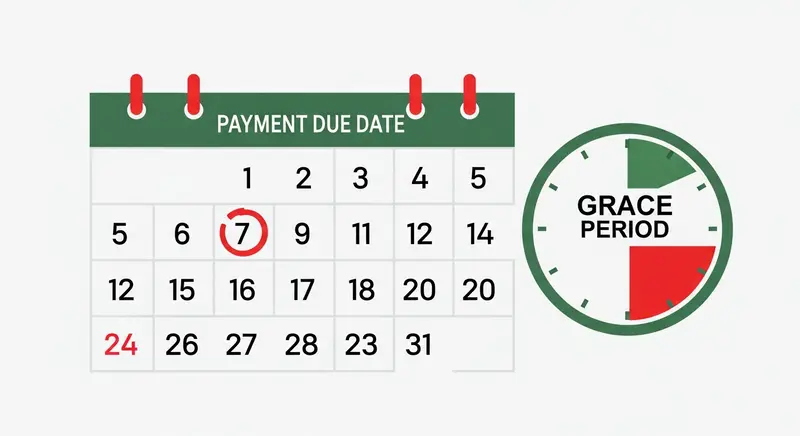
Life gets busy and sometimes you miss a payment. Here is exactly what happens to your life insurance policy, step by step, and what you can do about it.
If you are a single parent, your kids depend on you for everything. Here is how to make sure they are protected no matter what happens.
You are not limited to one life insurance policy. In fact, having more than one might be the smartest move. Here is when and why it makes sense.
Divorce changes everything, including your life insurance. Here is what happens to your policy, your beneficiaries, and your coverage obligations.
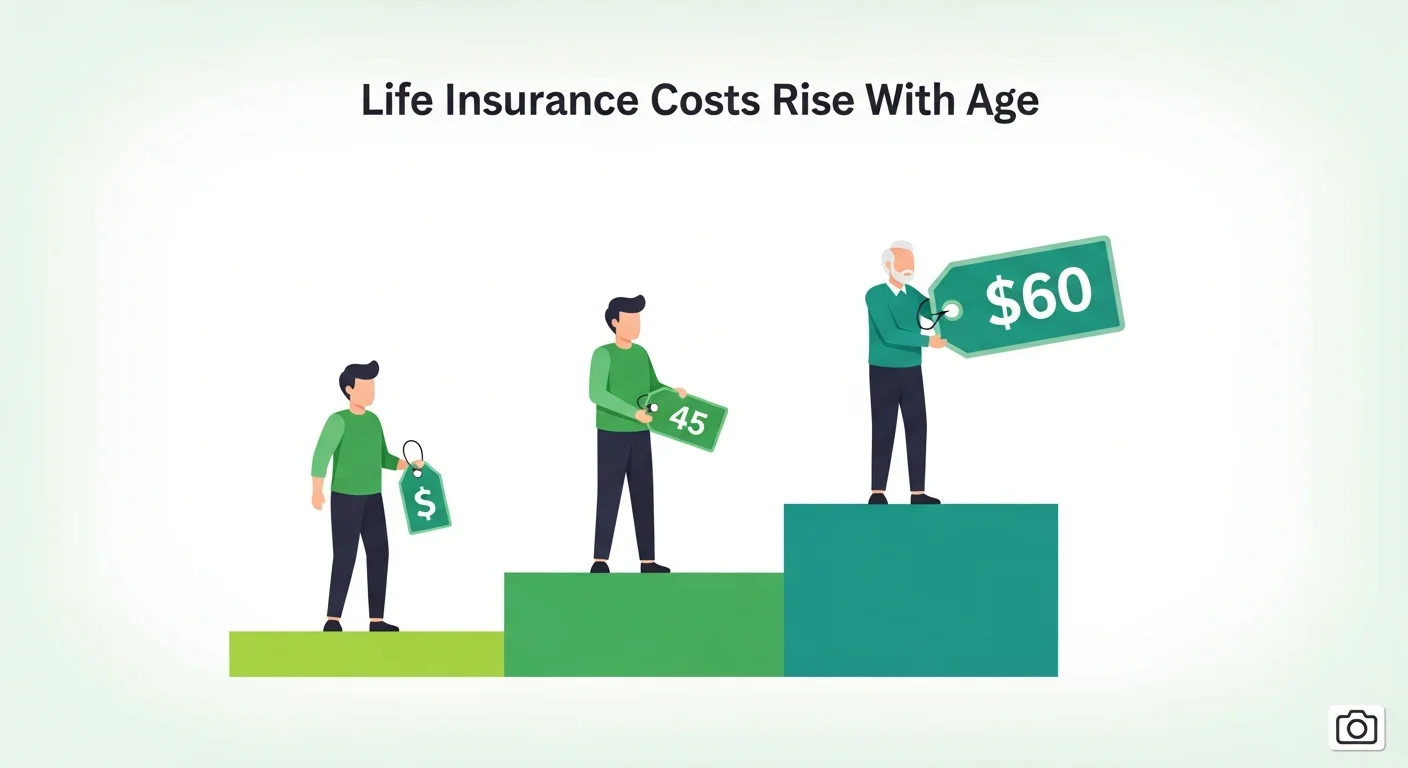
Quit wondering what insurance will set you back. I've laid out the actual monthly costs for term and whole life plans for 2026, broken down by your age.
If you smoke or vape, you’re going to pay more for life insurance. No way around that. But here is the real scoop on what it costs and what you can do about it.
Life changes, and maybe you need to cancel your policy. But before you just call up and say 'cancel,' make sure you know your options so you don't leave money on the table.
It’s a huge debate online. Buy cheap term, invest the savings, and you're set. But does the math work out, or is it just talk? Here is the honest truth.
Your beneficiary is just the person who gets the money. But you've got to pick the right one and set it up correctly, or you could cause a massive headache for your family.
It is a controversial topic. Some parents swear by it, others think it is a waste. Here is an honest, no-pressure breakdown.
Taking an antidepressant does not make you uninsurable. Here is what carriers actually care about and what they do not.
A denial is not the end. It is a detour. Here are your real options for getting coverage after being turned down.
A stay-at-home parent does not bring home a paycheck, but replacing what they do costs between $40k and $60k a year. Here is why you need to think about this.
Free life insurance from work sounds great. But it probably covers about 2 months of your family's bills. Here is why that is not enough.
Skip the needles and the nurse visit. But you will pay more for it. Here is an honest breakdown of no-exam life insurance and when it actually makes sense.
Forget the complicated formulas. Grab a pen and add up your monthly bills. That is your starting point. Here is the simple math.
Diabetes, high blood pressure, anxiety, cancer history. You can still get covered. Here is what carriers actually look at and what your options are.
Your term is ending and you are still here. That is great news. Here is what happens next and what your options look like.
Money is tight and your life insurance bill is due. Here is what to do before you let your policy lapse, and why canceling should be your absolute last resort.
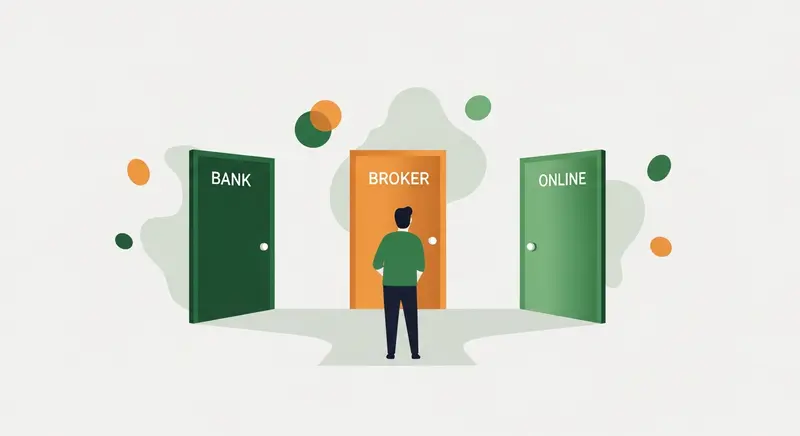
Banks, brokers, and online tools all sell life insurance. Here is an honest comparison of each option so you can pick the right channel for your situation.
No mortgage? That does not mean your family would not struggle without your income. Rent, groceries, car payments, and childcare do not stop just because you do not own a home.
You are 28, healthy, and feel invincible. Here is why buying life insurance now could be the smartest financial move you make this year.
Shopping for life insurance and drowning in quotes? Here is what to actually compare so you pick the right policy, not just the cheapest one.
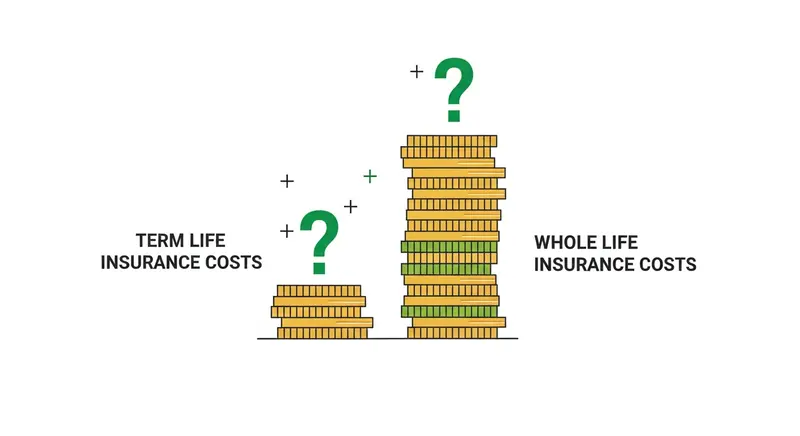
Whole life insurance costs 5-10x more than term. Here is an honest look at why, when it is actually worth it, and when you should skip it.
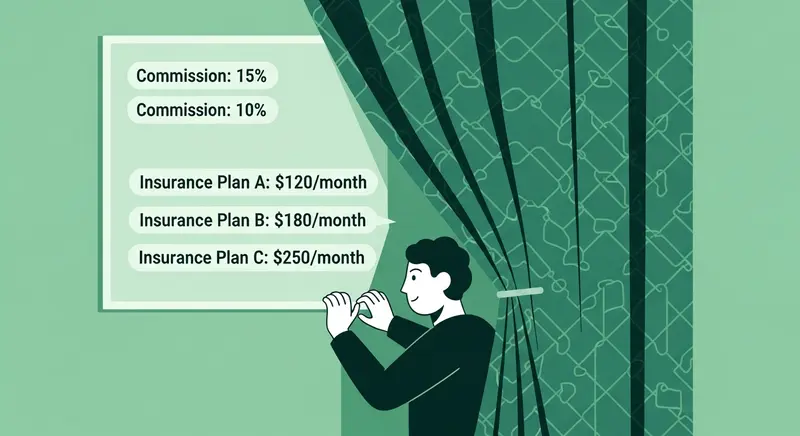
Worried your agent is pushing products you do not need? Here is how commissions actually work, the red flags to watch for, and what honest advice looks like.
Buying your first home in Illinois is exciting, but don't overlook life insurance. Learn why mortgage protection matters, how much coverage you need, and how Illinois' high property taxes make coverage even more essential.
Divorce in Illinois creates complex life insurance considerations, from court-ordered coverage to beneficiary changes. Learn what Illinois law requires and how to protect yourself and your children during and after divorce.
Every year you delay buying life insurance, premiums increase and health risks grow. See real cost comparisons by age for Illinois families and learn why acting now could save you thousands.
Life insurance after 50 in Illinois doesn't have to be complicated or unaffordable. Learn about guaranteed issue, simplified issue, and final expense options, plus strategies for getting the best rates as an older applicant.
Life insurance cash value can be a smart supplemental strategy for funding college in Illinois. Learn how it compares to 529 plans, its FAFSA advantages, and how Illinois families can use both tools together.
Life insurance riders can enhance your policy, but not all are worth the cost. Learn which add-ons Illinois policyholders should consider, from waiver of premium to child riders, and which ones you can skip.
Running a business in Illinois is risky enough. If you aren't sure how your company survives if you or a partner dies, you need a plan. Here is why life insurance matters.
Nobody likes dealing with taxes. But knowing the tax benefits of life insurance can actually save your family a good chunk of change. Here is the lowdown.
Your mortgage is likely your biggest monthly bill. Life insurance ensures your family doesn't have to sell the house if something happens to you.
This is the tough part. When the time comes, here is the exact, step-by-step guide to filing a life insurance claim.
One policy or two? Here’s the straight answer for most couples, plus the rare cases where a joint policy actually makes sense.
Think you're uninsurable because of a health hiccup or your past? Relax. Most people can still get covered. Here is the lowdown.
A medical exam for life insurance sounds intense, but it's really just a quick check-up. Here's how to prep and what they're actually looking for.
Your job gives you free life insurance. That's great! But it’s probably not enough to keep your family afloat. Here's why you need a backup plan.
If you're over 50 and worried you missed the boat on life insurance, don't be. You've got options—some that won't even break the bank.
Picking a beneficiary sounds simple, but getting it wrong can leave your family waiting for money they need right now. Here is how to get it right.
Life insurance riders can boost your coverage, but not all of them are worth the money. Here is which ones to get and which to skip.
Skip the medical exam and get life insurance faster. But is no-exam coverage right for you? Here is what you need to know before you decide.
Diagnosed with diabetes? You can still get life insurance. Here is what you need to know about your options and what you will actually pay.
Planning a move? Your life insurance follows you wherever you go. Here is what you need to do so your family stays covered.
Your spouse does not earn a paycheck, but try replacing everything they do. Here is why stay-at-home parents need coverage.
No kids, no spouse. Do you still need life insurance? Maybe. Here is how to figure it out.
Life in the city isn't cheap. Your life insurance should actually reflect your real cost of living. Here’s why and how.
Life insurance usually costs way less than people think. Here’s a look at what you’ll really pay in 2025.
Feeling lost on how much coverage to buy? We'll guide you through the math so you can stop guessing and protect your family.