What Happens to My Life Insurance If I Move to Another State?
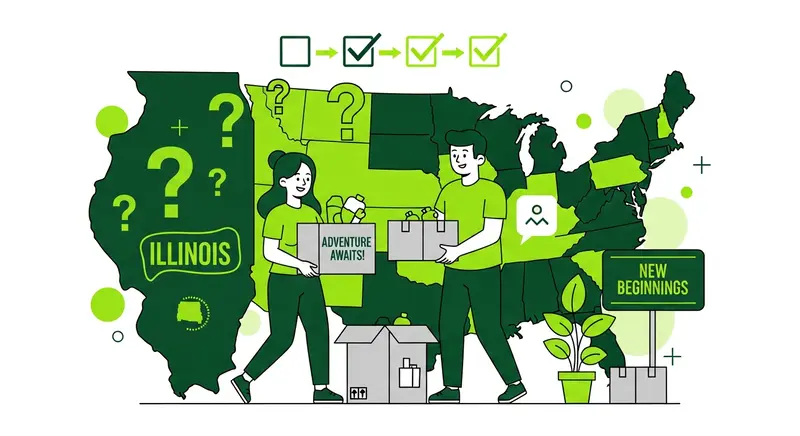
Moving is enough of a headache, right? So, here's the good news: your life insurance policy just moves with you. Wherever you go in the U.S., you're still covered.
MyMesi is based in Illinois, but we work across all 50 states with licensed partners. So, whether you're moving across the country or just to the next state, you're fine.
Your Policy Travels With You
Life insurance is pretty portable. When you move, nothing about your policy actually changes:
- Your death benefit stays the same
- Your monthly premium does not change
- Your coverage terms are locked in
- Your cash value keeps growing (if you have whole life)
- Your beneficiaries stay the same
- Your policy anniversary date does not move
You bought it, you own it, it goes where you go.
What You Need to Do When You Move
Even though the policy is active, you've got a couple of administrative things to handle.
Update Your Address
Get in touch with your insurance company to update:
- Your mailing address
- Your billing address
- Your phone number
- Your email address
Seriously, do this. If you miss a premium notice, your policy might lapse. And if something happens and your beneficiaries can't find the policy, that's a mess. Keep the info updated.
Review Your Beneficiaries
Since you're updating records, take a second to double-check:
- Primary beneficiaries
- Contingent beneficiaries
- Guardian designations for minor children
Different states handle beneficiary rules differently, especially regarding ex-spouses, common-law marriages, and community property laws. A quick check now saves a ton of grief later.
Let Your Agent Know
Just ping your agent. They can:
- Update your file
- Make sure you're getting proper service
- Answer questions about coverage in your new area
- Link you with a local agent if you want one
Situations That Could Affect Your Policy
Most moves are simple. A few cases are a bit different.
Moving Internationally
If you're leaving the U.S.:
- Most policies stay valid
- Some carriers have restrictions on living abroad
- Definitely contact your carrier before you leave
- You might need extra paperwork
- Claims could get a bit more complex for beneficiaries
High-Risk Locations
If you're moving to a war zone or somewhere super risky:
- It might void your coverage
- You might need higher premiums
- You might need policy changes
Check with your carrier first if you're heading to a conflict zone or somewhere with travel warnings.
State-Specific Products
In rare cases, a product is tied to a specific state—like certain pension-related life insurance, or some fraternal organization policies. Call your carrier to make sure yours moves with you.
Will My Rates Change?
Nope. Your rates are locked in when you buy the policy. It doesn't matter if your new state is cheaper or way more expensive—you pay the same.
If you decided to buy a brand new policy in your new state, sure, the rates might be different. But the original policy stays exactly as is.
Moving From One State to Another
No matter where you bought your policy:
- Your coverage continues unchanged
- Your rates stay the same
- Just update your address and keep paying premiums
If you're moving somewhere with a higher cost of living, you might want to look at your coverage amount. Make sure it's still enough to pay the mortgage and bills.
When to Think About a New Policy
Moving can be a good time to check if you need more or less insurance.
You might need more coverage if:
- You moved to a more expensive area
- You bought a bigger house/bigger mortgage
- Property taxes are higher
- Your new job pays more (more income to replace)
You might need less coverage if:
- Kids are grown and out of the house
- Mortgage is paid off
- You're near retirement
- You've got solid savings built up
Common Moving Scenarios
Job relocation to a different state: Your policy is fine. Just update your address. Keep in mind tax rules or cost of living might change, so see if your coverage still makes sense for mortgage, utilities, and childcare.
Retirement move to Florida: Policy continues. Update address/beneficiaries. If the house is paid off and kids are on their own, maybe you look into reducing coverage.
Military relocation: Policies are valid. Many carriers have programs for military families. Just keep updating that address if you move around a lot.
Your Moving Checklist
- Contact your insurance company
- Update your mailing address
- Update billing information
- Review and update beneficiaries
- Inform your agent of the move
- Reassess your coverage needs
- Keep all policy documents accessible
- Update your records with new contact info
- Make sure premium payments continue without interruption
The Bottom Line
Life insurance is easy to move. Coverage stays the same, rates stay the same, family stays protected. Just keep the address updated and pay the bills. Your family is protected regardless of your zip code.
Have Questions About Your Move?
Get a free quote in about 2 minutes at MyMesi. Whether you're moving to a new state or just checking your current coverage, we make it simple. No pressure, no confusing paperwork, just honest answers.