How Long Does It Take to Get Life Insurance? The Real Timeline
This is one of the big questions we get. People want the full timeline from the moment they start until the policy is actually in their hands. Here's the straight answer from MyMesi.
The Short Answer
For a healthy person, you're looking at maybe 2 to 6 weeks to get fully approved. If you skip the exam, you could be looking at 24 to 48 hours. But it really depends on the type of policy you pick, how healthy you are, and how fast you can get your documents turned in.
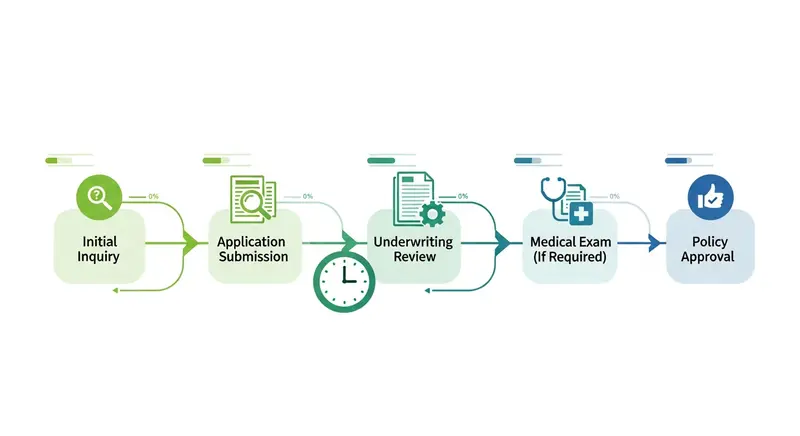
Step by Step: What Actually Happens
Application (15 to 30 Minutes)
You have to give them the basics:
- Your name, address, and age
- Your medical history
- Whether you smoke
- How much coverage you want and for how long
- Who gets the money
At MyMesi, we keep this to about 15 minutes online. Avoid paper applications—they're just slower.
Medical Exam (If Required, 1 to 2 Weeks to Schedule)
If you need an exam, it goes like this:
- A professional comes to your place or work.
- They do a quick check of your pulse, blood pressure, height, and weight.
- They take a bit of blood and urine.
- The visit takes about 20 or 30 minutes.
- The results get to the company in about 5 to 10 business days.
Not every policy needs this, though.
Underwriting (1 to 4 Weeks)
This is the insurance company doing their homework:
- Looking at your application
- Checking the exam results
- Peeking at your prescription drug history
- Looking at your driving record
- Seeing if you've applied for insurance before
If you're healthy and it's a simple case, you're usually through this in 1 to 2 weeks. If you have some health conditions or you're a bit older, it can drag out to 3 to 6 weeks.
Approval and Policy Delivery (3 to 5 Business Days)
Once they say yes, you look over the policy, sign, and pay the first premium. That's when your coverage kicks in.
Total Timeline
- No-exam policy, healthy: 24 hours to 7 days
- Standard policy with exam, healthy: 2 to 4 weeks
- Policy with health issues: 4 to 8 weeks
- Complex cases (age, multiple health issues): 6 to 12 weeks
No-Exam vs. Traditional Exam Policies
No-exam policies skip the doctor visit. They just check your app, your medical records, and sometimes call you for a chat.
Pros:
- Super fast, sometimes same-day.
- No needles or scheduling appointments.
- Good if you're generally healthy.
Cons:
- Premiums cost a bit more (10% to 20% higher).
- There's usually a cap on how much coverage you can get ($1M to $2M).
- Not for everyone if you have specific health issues.
Traditional exam policies take longer, but you usually get the best price. If you want the cheapest monthly bill and you're healthy, the wait is worth it.
What Slows Things Down
At MyMesi, we see the same things cause delays:
- Incomplete applications. If you leave stuff out, the company has to go back and forth with you. Just double-check your info.
- Waiting to schedule the exam. Book it the second you can.
- Medical records requests. If they need to call your doctor, it can add a few weeks while you wait for the office to reply.
- Specific health issues. Things like sleep apnea, heart trouble, or mental health checks take extra time. It's not a dealbreaker, just more paperwork.
- Large policies. If you want $2M+ in coverage, they're going to verify your finances.
- Tobacco use. If you smoke or vape, expect more review. Be honest from the start.
How to Speed Things Up
- Apply online. Skip the paper forms.
- Be totally complete. Don't skip questions.
- Schedule your exam right away.
- Have your doctor's name and info handy.
- Be honest. They'll find out if you're not.
- Answer questions fast. Respond to follow-ups the same day.
What Happens If You Need Coverage Right Now?
- Temporary coverage. Some carriers offer a "conditional receipt" that covers you from the moment you apply and pay your first premium.
- No-exam accelerated policies. Can be done in 24-48 hours for young, healthy applicants.
- Guaranteed issue policies. No health questions at all, but they're expensive and have a waiting period (2-3 years) before they pay out the full benefit. Last resort only.
Real Timeline Examples
- Sarah (32, healthy): Applied Monday, no-exam, approved Wednesday. Total: 2 days.
- James (45, controlled blood pressure): Applied, scheduled exam, got results in 8 days, underwriting took 2 weeks. Total: 4 weeks.
- Linda (58, diabetes/cholesterol): Applied, exam, had to request doctor records, underwriting took 5 weeks. Total: 7 weeks.
The Bottom Line
Usually, you're looking at 2 to 4 weeks. Want it fast? Skip the exam. Want the best rate? Do the exam and wait it out.
The real worst-case scenario? Not applying at all. You just keep getting older, and your rates keep going up. Do it now.
Get Started With MyMesi Today
Ready to see your options? MyMesi can get you connected with top carriers in about 2 minutes. Get a quote, compare your stuff, and put it in gear. Your family needs the plan.