Is My Insurance Agent Trying to Sell Me Something I Don't Need?
So you’re with an agent. Maybe they found you, maybe a friend sent them your way. But you’re sitting there thinking, "Are they actually helping me, or just trying to get that commission?" It’s a totally valid question. Honestly, you should be asking it.
At MyMesi, we like being upfront about this stuff. Let’s talk about how the money works and what you should look out for.
How Insurance Agent Commissions Actually Work
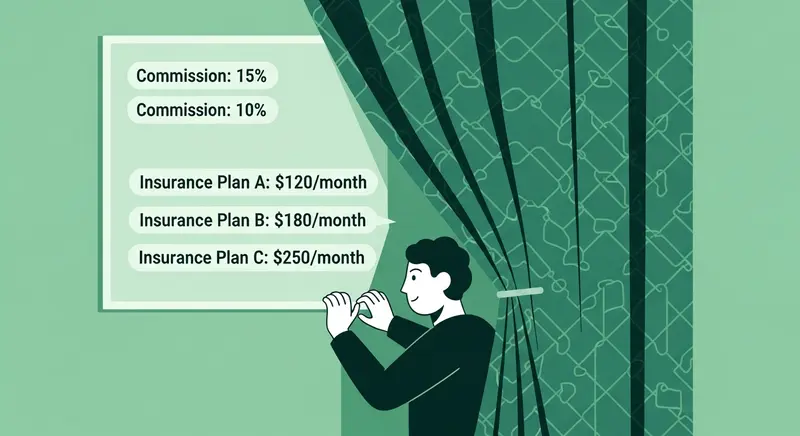
Here’s the deal most people don't talk about. The insurance company pays the agent a commission when you buy a policy. You don’t see it as a separate fee—it’s just rolled into the premium. But the pay structure is different depending on what you buy:
- Term life: The agent makes a smaller cut, usually 50-100% of the first year's premium.
- Whole life: The agent makes a huge cut, usually 80-110% of the first year's premium. And remember, the premiums themselves are 5-10 times higher for whole life.
Think about it: if you pay $30 a month for term, the agent might make $180-$360. If they sell you a $300-a-month whole life policy, they could be making $2,880-$3,960. It’s a massive difference. Now, that doesn't mean every agent pushing whole life is a crook, but you should definitely know why they’re pointing you that way.
Red Flags That Your Agent Is Not Looking Out for You
Watch out for these:
- They won't even discuss term insurance. If they act like it doesn't exist, wonder why.
- They try to pressure you. If they say, "Decide today or the rate is gone," that’s just a sales tactic.
- They talk in code. If they can’t explain the product in regular, plain English, walk away.
- They push super complex stuff. Indexed products, variable this-and-that—if it takes 40 pages to explain, you don’t need it.
- They get mad when you ask questions. A good agent won’t mind at all.
- They don't ask about your actual life. If they haven't asked about your debts, your rent, or your kids, they’re just guessing.
Signs Your Agent Is Giving You Honest Advice
A good agent does the opposite:
- They ask about your real life. Your bills, your debt, your monthly costs.
- They explain both term and whole life so you can compare.
- They show you quotes from a bunch of different companies.
- They make sure the coverage is actually something you can afford long-term.
- They’ll answer if you ask them about their commission.
- They don't rush you.
Why People Get Burned (The Northwestern Mutual Problem)
You might have seen stuff on Reddit about big agencies pushing expensive whole life policies on 25-year-olds who really just need a cheap term policy. It’s a classic move: they push a $200-$400 a month policy to a young professional, talk about "building wealth," and two years later the person realizes they're overpaying and drops it. Whole life has its place, but for a 28-year-old just looking to replace their income, cheap term is almost always the move.
How MyMesi Is Different
We keep it simple. We do term and we do whole life. That’s it. We’re independent, so we don't work for just one carrier. We can search a bunch of top-rated companies at once to see who gives you the best price.
- You get quotes in about 2 minutes.
- You see the prices side by side.
- No pressure.
- You pick what works for you.
Life insurance is just a bridge. It’s 240 months of knowing the rent gets paid and the kids have food. Because the bills don't stop just because someone is gone.
How to Protect Yourself When Shopping for Life Insurance
- Do some reading before you meet them. Know the difference between term and whole.
- Ask them how they get paid. It’s your money, you have the right to know.
- Get at least two or three quotes from different places.
- Don’t sign anything unless you can explain it to your partner in two minutes.
- Trust your gut. If it feels weird, get out.
Get a Straight Answer in 2 Minutes
Forget the sales pitch. We let you compare quotes from top carriers in about 2 minutes. See the real numbers, ask your questions, and do it on your own time. No games.