Term vs. Whole Life: Which one should you pick?
Let's get straight to it without the sales fluff. At MyMesi, we mostly deal with two kinds of insurance: term and whole life. Here is the lowdown on what they do so you can figure out what fits your family.
What is Term Life?
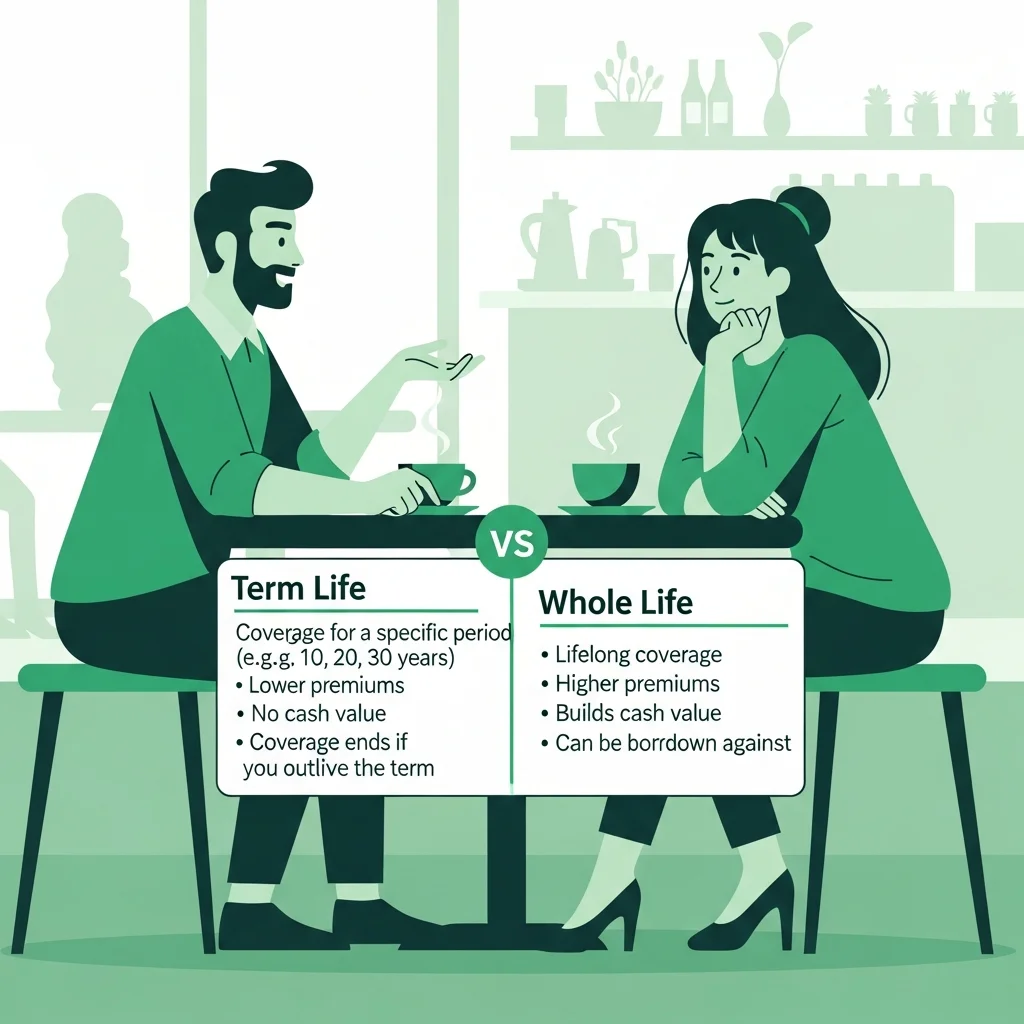
It is pretty straightforward. You're covered for a set amount of time—like 10, 20, or 30 years. You pay a monthly bill, and if the worst happens while the policy is active, your family gets the payout. That is literally it.
Why most families stick with term:
- It is way easier on the wallet than whole life.
- There is no hidden stuff. You pay, you get covered.
- You can pick exactly how long you need the protection.
- You get way more coverage for your money.
Think of it as a bridge for the years when your family really needs your income—like when you're paying off the mortgage, dealing with car notes, childcare, and the pile of groceries you buy every week. The bills don't care if you're here or not, so this keeps things running.
For perspective, a 35-year-old who doesn't smoke can snag $500,000 of 20-year term coverage for about $25-40 a month. That is cheaper than what you're probably paying for streaming services every month.
What is Whole Life?
This one covers you for your entire life, provided you keep paying the premiums. Plus, it builds up a bit of cash value over time that you can borrow against.
Why people go for whole life:
- It never expires.
- You're technically building a little savings bucket.
- The premium stays the same forever.
- The death benefit is guaranteed.
But here is the catch: it costs a lot. We're talking 5-10 times the price of term for the exact same payout.
So, which one do you need?
Term life is likely for you if:
- You want to make sure the house is paid off.
- You have kids who are still growing up.
- You want the most "bang for your buck" in terms of coverage.
- You just want to make sure the monthly bills are covered for the next few decades.
Whole life might be for you if:
- You want coverage that lasts until you're gone, no matter when that happens.
- You've already got your retirement and savings accounts maxed out.
- You've got estate planning stuff to worry about.
- You really want that cash value feature.
Most families? Just stick to Term.
Honestly, most people just want to make sure their home is secure and the kids are okay. Term life does exactly that without breaking your budget. Your family doesn't need a jackpot—they need a bridge. They need 240 months of knowing the mortgage is handled and there is money for the essentials while they figure out the next chapter.
Get a quote in 2 minutes
We make this part super easy. You can get a free quote from solid carriers and see what works for you. No pressure, no stacks of paperwork, just the numbers.