Life Insurance Riders Explained: Add-Ons Worth Considering for Your Family
When you're shopping for a policy, you'll hear about "riders." Think of them as optional features or add-ons. Some are actually pretty useful, but others? Probably not worth your cash. Here's the plain-English breakdown.
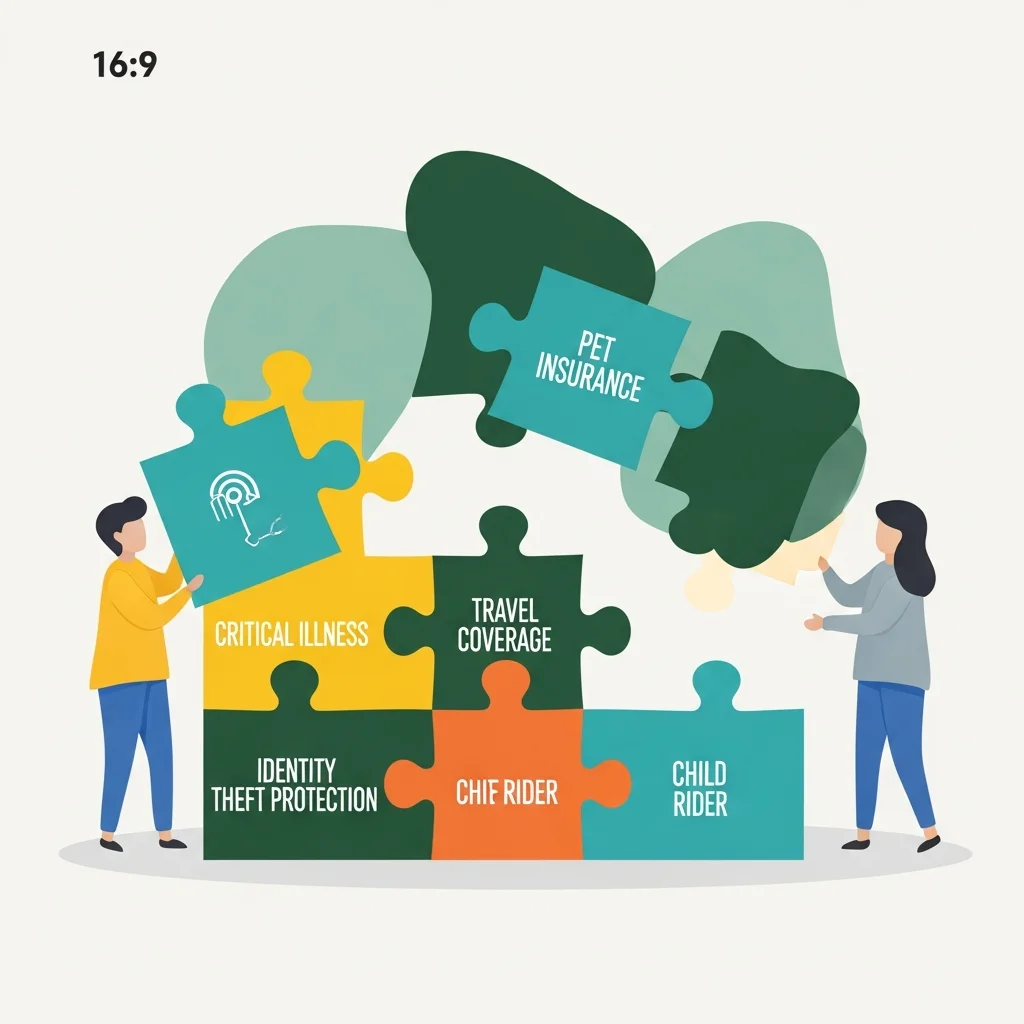
What is a Life Insurance Rider?
It's just an extra piece attached to your main policy, kind of like getting extra features on a new car. The policy works fine without them, but sometimes they're nice to have.
Keep these basics in mind:
- They cost extra, usually added onto your monthly bill.
- Most are optional.
- Some are actually free.
- Usually, you pick these when you first sign up, but sometimes you can add them later.
Riders Worth Getting
Waiver of Premium Rider
Basically, if you get disabled and can't work anymore, the company covers your insurance payments for you. Your policy stays active even though you aren't paying a dime.
For example, say you're in a wreck and can't work for two years. Instead of shelling out $50 a month, the company picks up the tab. Your family stays covered.
It usually runs about $2-5 per month per $100,000 of coverage. I'd say this is a must for breadwinners, the self-employed, or anyone without a separate disability plan. Honestly, it's cheap protection for your protection.
Accelerated Death Benefit (Terminal Illness) Rider
If you're diagnosed with a terminal illness—typically if you have 12-24 months left—this lets you pull out 25-100% of your death benefit early. You can use that money for hospice, medical bills, or just making memories with the family.
If you have a $500,000 policy and get a terminal diagnosis, you could grab $200,000 early. It's often free, so honestly, there's no reason not to take it.
Children's Term Rider
This adds a small bit of coverage, maybe $10,000-25,000, for all your kids—current and future—under one bucket. It's usually $5-10 a month for the whole group.
It helps with funeral costs and guarantees that your kids can get their own policies later regardless of their health. If you have kids or plan to, it's a solid value.
Guaranteed Insurability Rider
This is great if you're young and healthy. It lets you buy more insurance later without needing a new medical exam. If you buy $500,000 today and develop diabetes later, you could still add $250,000 more later on. It usually runs $10-20 a month and is perfect for anyone expecting their income to jump or who wants to lock in their insurability early.
Conversion Rider
This lets you swap a term policy for a whole life policy without proving you're healthy. It's often free. If it's free, just take it—it gives you flexibility if your health changes.
Riders That Are Usually Not Worth It
Return of Premium Rider
It sounds nice: if you outlive your term, you get your money back. But it's pricey. If your policy is $50/month, this might push it to $120. You're paying an extra $70/month ($16,800 over 20 years) to potentially get back $28,800. You're usually better off investing that extra $70 yourself.
Accidental Death Benefit Rider
This doubles the payout if you die in an accident. But your family needs the same amount of money whether you die from an accident or a sickness. Only about 5% of deaths are accidental. Just buy more base coverage instead; it's a better use of the $5-15 monthly fee.
Critical Illness Rider
This pays a lump sum if you get something like cancer or have a stroke. It's okay, but look into a standalone policy—often better value.
Long-Term Care Rider
This covers some nursing home stuff, but the benefits are pretty limited compared to a real long-term care policy. Keep them separate.
What It Costs: A Real Example
Say you're 40, healthy, and buying a $750,000, 20-year term policy. Base cost is $60/month. Add the good stuff:
- Waiver of Premium: +$4
- Accelerated Death Benefit: Free
- Children's Rider: +$8
- Conversion Option: Free
- Total: $72 per month
You're paying $12 extra per month for some real peace of mind. For most people, that's worth it.
Our Recommendations
- Get if free: Accelerated death benefit, conversion option, disability waiver.
- Serious consideration: Waiver of premium (if you're self-employed), children's rider, guaranteed insurability (if young).
- Skip: Return of premium, accidental death benefit.
Questions to Ask
- What problem am I actually solving here?
- What's the total cost over 20 years?
- Is there a cheaper way to fix this?
- Will I actually use it?
- Do I already have this covered somewhere else?
The Bottom Line
Keep it simple. Grab the cheap/free riders that matter and ignore the expensive ones. You can get quotes at MyMesi whenever you're ready to see the real numbers.