Should I Buy Life Insurance Through My Bank or a Broker?
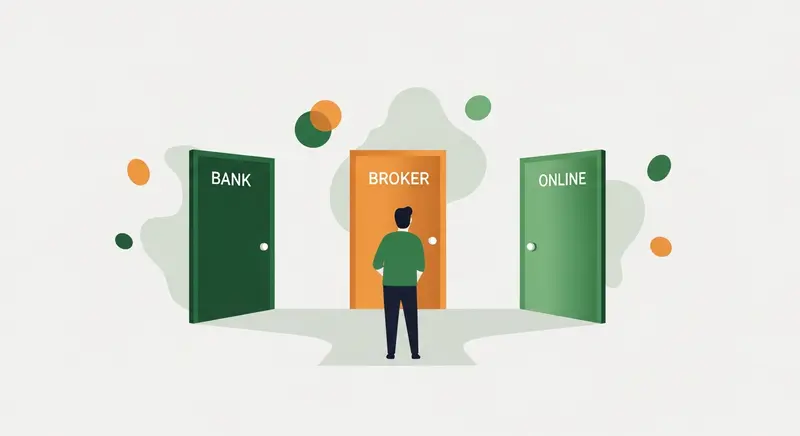
So you know you need life insurance. Great. Now comes the part where you figure out where to actually buy it. Your bank is pushing their plan, your friend said talk to a broker, and then you’ve got all these online tools popping up. It’s confusing, and honestly, the wrong choice could cost you hundreds of dollars a year. Let's look at it for real.
Option 1: Buying Through Your Bank
Banks love to offer life insurance. It’s super convenient since you already bank there. They might even try to sell it to you when you’re just there to deposit a check.
The pros:
- Super convenient.
- You already know and trust the bank.
- It might be bundled with your other accounts.
The cons:
- They usually only sell one or two carriers. You’re definitely not seeing the full market.
- Bank employees aren't really insurance experts. They don't know the deep stuff.
- You get what you get. Very little room to customize.
- Because they have limited options, the price is rarely the best.
- They have sales quotas, so they might just be pushing what’s best for the bank, not you.
Bottom line: It's easy, but it’s kind of like buying a car from the very first lot you stop at. You're probably overpaying.
Option 2: Buying Through a Broker or Independent Agent
A good broker works for you, not one specific insurance company. They can shop your info across a bunch of different carriers to see who will give you the best deal.
The pros:
- They have access to tons of companies.
- They can compare quotes side-by-side.
- They actually know the ins and outs of health issues and which carriers like which profiles.
- If your situation is complicated, they can save your bacon.
- They are technically on your side.
The cons:
- Quality is all over the place. Some brokers are great, some are just trying to make a quick buck.
- You have to do the legwork to find a good one.
- It takes time to book calls and chat.
Bottom line: A good independent broker is your best bet, but you really have to vet them. Ask them how they get paid and how many companies they work with.
Option 3: Buying Online
Online tools have totally changed the game. You can basically get your quotes and sign up without ever having to talk to a human.
The pros:
- It is lightning fast.
- No pressure. No salesperson trying to upsell you.
- You can compare a bunch of carriers in seconds.
- You can do it in your sweatpants at 2 AM.
- Prices are clear and you know what you’re paying.
The cons:
- If you don't know what you're doing, you might pick the wrong thing.
- Some sites only show you the partners they get paid by.
- If you have health stuff, you might need a human to help you navigate it.
Bottom line: This is great if you’re healthy and just want to get it done fast.
The Best of Both Worlds: Online Tools with Human Support
We think the best way is to start online, but make sure you can talk to someone if you get stuck. That’s how MyMesi works. You get quotes from top companies in 2 minutes, but if you have a headache and need a real expert, you can just ask. Our agents are independent, so they aren't tied to one company. They just help you find the best deal.
And we cover all 50 states, so it doesn't matter where you live; you get the same options.
What to Ask No Matter Where You Buy
Before you sign anything, ask these questions:
- How many companies are you comparing? More is always better.
- What is the carrier's A.M. Best rating? Keep it A- or better.
- Can I convert this later? You want to know if you can switch to a permanent policy without an exam.
- What about riders? Ask about things like an accelerated death benefit, which is super handy.
- How does the application actually work? Is it a full medical exam, or something simpler?
- How do you get paid? Be direct. You want to know if they are pushing something because it pays them better.
A Side-by-Side Comparison
| Feature | Bank | Independent Broker | Online (MyMesi) |
|---|---|---|---|
| Number of carriers | 1-2 | 10-30+ | Multiple top-rated |
| Price competitiveness | Limited | Strong | Strong |
| Expert guidance | Sometimes | Yes | Yes, on demand |
| Convenience | Medium | Requires scheduling | High |
| Pressure | Low to medium | Varies | None |
| Speed | Medium | Slower | Fast (2 minutes) |
| Customization | Limited | High | High |
The Bottom Line
Where you buy matters because the price difference is real. One company might charge you $28, another might charge $38 for the exact same coverage. That’s $120 a year down the drain if you don't look around. It’s a bridge for your family, so make sure you get the best deal.
Compare Your Options in 2 Minutes
Ready to see what’s out there? MyMesi lets you compare quotes from top-rated carriers in about 2 minutes. No bank appointment. No broker scheduling. Just your real numbers, right now.