Is Life Insurance Taxable? The Simple Tax Guide You Need
Most people get way too stressed about the tax side of life insurance, but it's really not that complicated. Let's just strip away all the weird talk and look at the facts.
The Short Answer
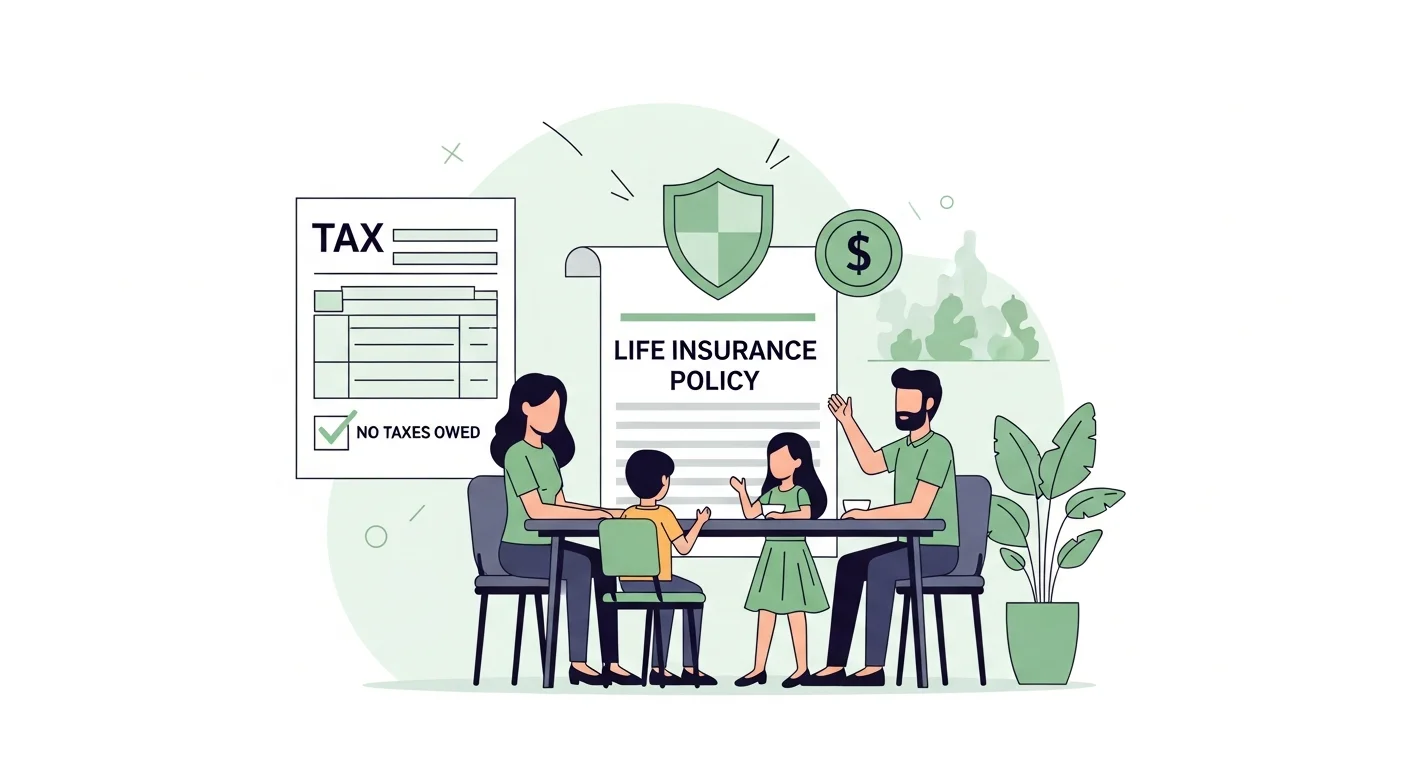
Usually, life insurance death benefits don't have any tax attached. The person you name gets the full check. No income tax, no capital gains, nothing.
So, if you've got a $500,000 policy, your beneficiary gets exactly $500,000. The IRS doesn't get a penny of it.
This holds up for both term and whole life policies. It doesn't matter how big the policy is or who you pick as the beneficiary. It's almost always a tax-free deal.
When the Death Benefit IS Tax-Free
- Lump sum payment to a named beneficiary. This is the normal way it's done. Spouse, kids, trust—they get the whole amount tax-free.
- Payment to a trust for your minor kids. Still tax-free. The trustee just handles the money based on the trust rules.
- Payment split between a few people. Each person gets their share tax-free, even if you split it three ways or whatever.
When Taxes Might Apply
There are a few weird spots where taxes could pop up. Most people never run into these, but you should probably know they exist.
Situation 1: Interest earned on the death benefit. If the insurance company hangs onto the money for a while before they cut the check—like if it's sitting in an interest-bearing account—you've gotta pay tax on that interest. The death benefit itself stays tax-free, but that extra interest is treated as normal income.
Example: The payout is $500,000, but they process it over 6 months and end up paying $504,000 because of interest. That $500,000 is clean, but the $4,000 interest is taxable.
Situation 2: The policy is part of a massive estate. Federal estate taxes only trigger if your total estate is worth over $13.61 million (that's for 2025, and it changes with inflation). If you are somehow worth more than that, the life insurance payout could get caught up in estate taxes. If you're in that bracket, people usually set up an irrevocable life insurance trust (ILIT) to keep the policy out of the taxable estate.
Situation 3: You sold your policy (life settlement). Selling your policy for a cash payout is a different beast. It might be partially taxable, and the math depends on what you put in versus what you got out. This is pretty rare, but definitely talk to a tax pro if you're thinking about selling.
Situation 4: Employer-paid group life insurance over $50,000. If you get life insurance through your job and the benefit is over $50,000, you pay tax on the cost of that extra coverage. You'll see it as "imputed income" on your W-2. The death benefit is still tax-free for your family, but you pay a tiny bit of tax on that premium coverage while you're still working.
Cash Value: The Tax Rules
If you've got a whole life policy with cash value, the tax rules change a bit depending on how you use the money.
- Policy loans (borrowing against your cash value): Tax-free. You're taking a loan, not a withdrawal. But if the policy lapses or you surrender it while you still have a loan balance, that could turn into a taxable event.
- Withdrawals up to your basis: Tax-free. Your "basis" is just the total premiums you've paid in. Since you already paid tax on that money, you don't get taxed again for taking it out.
- Withdrawals above your basis: Taxable. Anything over what you paid in is taxed like regular income.
Example: You paid $40,000 in premiums. Your cash value is $65,000. If you pull out $40,000, you pay nothing. If you pull out $50,000, that $10,000 over your basis is taxed as ordinary income.
Surrendering the policy: If you hand the policy back to the company for the cash surrender value, you owe taxes on any amount that exceeds your basis.
Example: You paid $60,000 in total. The surrender value is $85,000. You're paying income tax on the $25,000 gain.
Section 1035 Exchanges: Tax-Free Swaps
A 1035 exchange is basically a way to swap one life policy for another without a tax headache. It comes from Section 1035 of the Internal Revenue Code.
How it works:
- You move the cash value straight from the old policy to a new one.
- You never touch the money yourself.
- No taxes trigger.
- The new policy picks up your old tax basis.
What qualifies:
- Life insurance to life insurance: Yes.
- Life insurance to annuity: Yes.
- Annuity to life insurance: No.
- Annuity to annuity: Yes.
People usually use these to get away from high-fee policies, switch to a more stable carrier, or change up their coverage. You've gotta do this through the insurance companies directly—don't try to cash out and buy a new one yourself, or you'll get hit with taxes. Work with an agent to get the paperwork right.
Dividends From Whole Life Policies
Some whole life policies pay dividends, and here's the deal on those:
- Dividends up to total premiums paid: Not taxable. It's just treated as a return of premium.
- Dividends over total premiums paid: Taxable as ordinary income. This is rare and usually only happens on older policies.
- Dividends left with the company to earn interest: The dividend might be fine, but the interest it earns is taxable.
A Quick Summary
- Death benefit paid to beneficiary: No (taxable)
- Interest earned on held death benefit: Yes (taxable)
- Estate over $13.61 million: Possibly (taxable)
- Policy loan from cash value: No (taxable)
- Cash value withdrawal up to basis: No (taxable)
- Cash value withdrawal above basis: Yes (taxable)
- Policy surrender (gain over basis): Yes (taxable)
- 1035 exchange: No (taxable)
- Employer coverage over $50,000: Yes (small amount) (taxable)
- Dividends up to premiums paid: No (taxable)
- Interest on accumulated dividends: Yes (taxable)
When to Talk to a Tax Professional
Usually, life insurance taxes are easy. Death benefit is tax-free, and that's it. But talk to a pro if:
- Your estate is worth over $10 million.
- You're thinking about selling your policy.
- You're surrendering a whole life policy that has a lot of cash value.
- You're trying to do a 1035 exchange and need to be sure it's done right.
- You've got a complicated estate plan with trusts.
MyMesi Keeps It Simple
Life insurance shouldn't be a nightmare, and the tax stuff shouldn't be either. At MyMesi, we help families in all 50 states get covered without the corporate speak. No hidden nonsense. You can grab a free quote in about 2 minutes and see what your actual costs look like. Bills keep coming, so make sure your family has a plan that works.