How much life insurance do you actually need?
This is the #1 question we hear. There is no "magic" answer, because it all comes down to your personal bills. It is about making sure your family can keep the lights on, the mortgage paid, and the kids fed if you aren't around.
Quick math to start
A solid starting point is aiming for 10-12 times your annual income. Making $75,000? Aim for $750,000 to $900,000. Use that as a baseline, but remember it could be more or less depending on your life.
The DIME method (A way better way to calculate)
If you want to be precise, add up these four things:
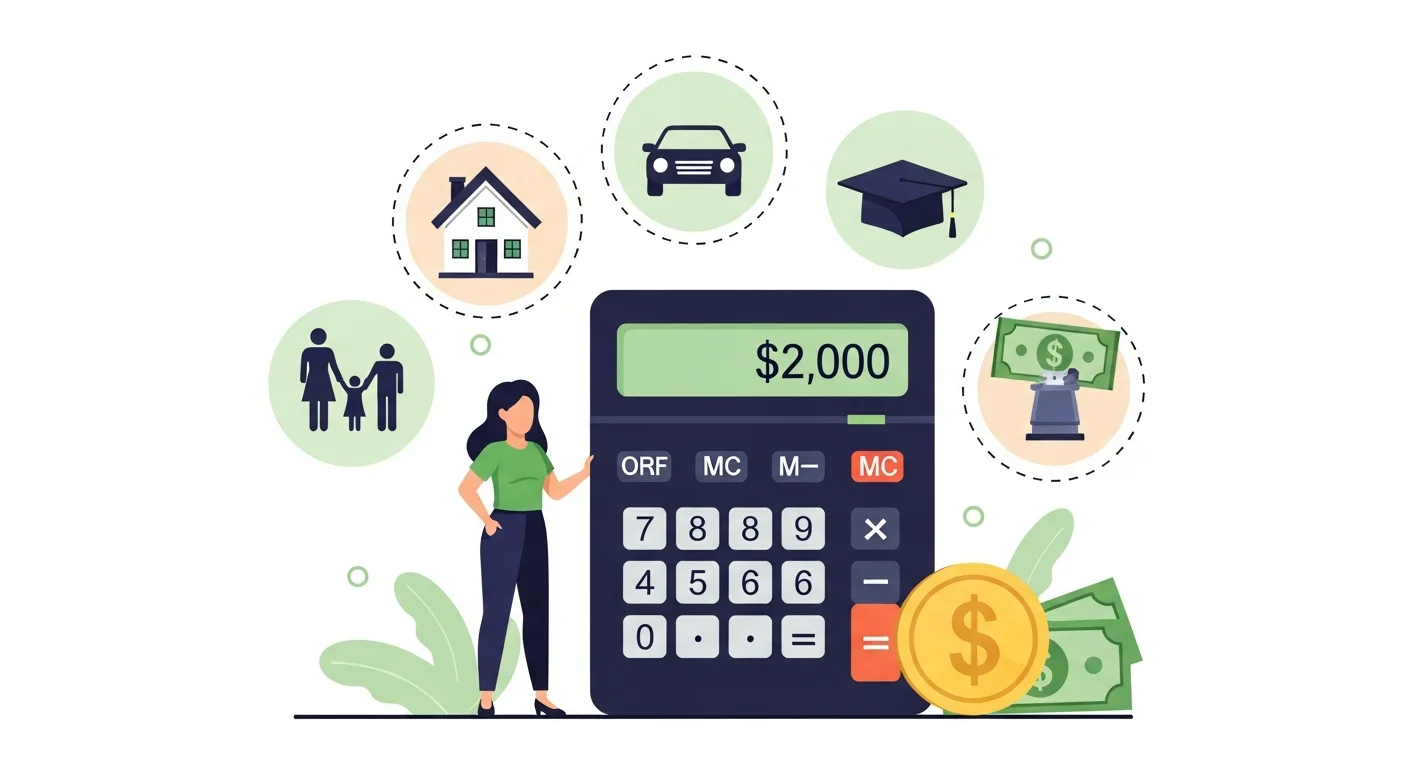
D for Debt: Add up everything you owe. Mortgage (the average is around $240,000), credit card balances, car loans, student loans—all of it.
I for Income: How many years of your salary does your family need to keep going? If you're 40, earn $80,000, and plan to retire at 65, you might want $80,000 x 25 = $2,000,000.
M for Mortgage: This is often the biggest chunk, so make sure it's fully covered.
E for Education: College is pricey. State schools run about $15,000-30,000 a year, so figure $60,000-120,000 per kid for a four-year degree.
Keep these in mind too
Where you live matters. Living in a big city means higher rent or mortgage, expensive groceries, and more for transit. Match your coverage to your real-world monthly spending.
Don't ignore property taxes. They can be a massive bill every single year. Make sure the life insurance amount accounts for keeping the house even with those taxes.
College costs add up. Plan for at least state-school prices ($60k-$120k per child) so you aren't leaving your family short.
An example for a normal suburban family
Let's run the numbers for a typical situation:
- Income: $90,000
- Mortgage: $280,000
- Car loan: $25,000
- Credit cards: $8,000
- College: $200,000
- Final expenses: $15,000
- Emergency fund: $30,000
Total comes out to about $558,000. Throw in a little extra for inflation and surprises, and you're looking at $600,000 to $750,000.
Don't forget the stay-at-home spouse
If your spouse stays home, they do a ton of work that costs real money to replace—like childcare ($30k-$50k a year), cooking, driving, and errands. They should have at least $250,000-500,000 in coverage too.
Life changes, so update your policy
Re-evaluate your numbers when you get married, have a baby, buy a house, or get a raise. Don't just set it and forget it.
What people usually go for
Most of our clients at MyMesi land in these ranges: young families grab $500,000-$1,000,000, mid-career folks aim for $750,000-$1,500,000, and high earners often need $1,000,000 to $3,000,000+.
Get your number in 2 minutes
Quit the guessing game. Use our tool to get a quote in 2 minutes. No sales calls, no pressure, just the facts.