The 'Buy Term and Invest the Difference' Idea: Does it Actually Work?
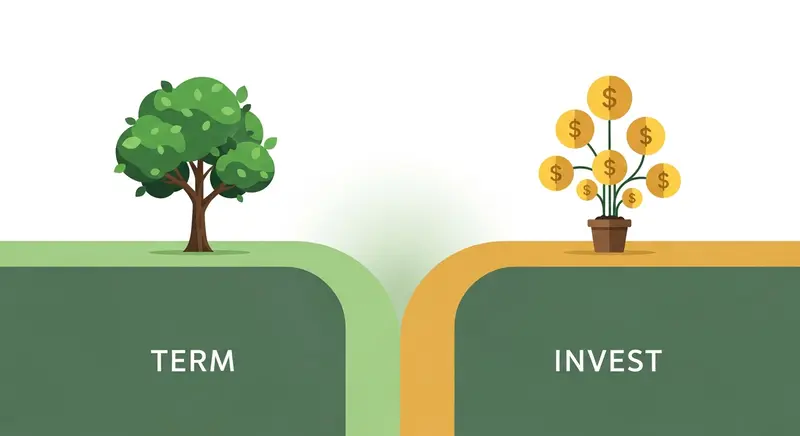
This is one of those topics people love to argue about on Reddit or at family dinners. It’s simple: Buy a cheap term life policy instead of paying for expensive whole life, and then put the extra cash into investments. Over 20 or 30 years, that investment account should end up worth more than a whole life policy would have been.
Sounds great on paper. Does it happen in real life? Let’s look at the math.
How it works
Imagine you’re 35, you don't smoke, and you have two choices:
Choice A: Whole life insurance
- $500,000 in coverage
- Cost: $450 per month
- Builds some cash value over time
- Covers you your whole life
Choice B: Term life insurance
- $500,000 in coverage for 20 years
- Cost: $30 per month
- No cash value
- Coverage stops after 20 years
You save $420 every month by picking the term policy. The theory is that you take that $420 and invest it every single month for those 20 years.
The math (when it goes well)
If you invest that $420 a month for 20 years and get a 7% average annual return (which is roughly what the stock market does over time), here is what you get:
- Total you put in: $100,800
- What it’s worth after 20 years: About $218,000
In that same time, a whole life policy might have a cash value of $120,000 to $160,000. So, yeah, in this perfect scenario, you’re ahead by $60,000 to $100,000. The math really does work.
The problem (when it doesn't work)
Most people don't actually do this for 20 years. Here’s why it’s harder than it looks:
You have to actually stick to it. Every single month. For two decades. No skipping. And no taking money out for a new car or a kitchen reno. If you’re not a disciplined saver, this is going to be really hard.
The market doesn't go up in a straight line. It averages 7% over a long time, but it has bad years. If your 20-year window hits a rough patch, your total will be much lower.
Look at the same $420/month at different returns:
- At 4% return: $153,000
- At 7% return: $218,000
- At 10% return: $315,000
At 4%, you’re barely doing better than the whole life policy. The problem is you can't control the market.
Your term policy ends. After 20 years, your coverage is done. If you’re 55 and still need insurance, you have to buy a new policy. And it’s going to be way more expensive. A 55-year-old might pay $150 to $250 a month for $500,000 in coverage. Plus, if you’ve had health issues, you might not even qualify at all.
Taxes. Whole life cash value grows without you paying taxes on it every year. Your investment account might hit you with capital gains taxes. You could use a Roth IRA to dodge taxes, but you can only put in a limited amount per year (in 2025, the limit is $7,000), so you can't put that full $420/month in there.
Who should actually try this?
- You are super disciplined and won't touch the money.
- You’re okay with the market going up and down.
- You’ve already maxed out your 401k and IRA.
- You’re young and healthy, so your term rates are cheap.
- You’re sure you won't need insurance after 20 or 30 years.
Who should think about whole life instead?
- You want coverage for your entire life, no matter what.
- You want a guaranteed cash value that doesn't depend on stocks.
- You’ve already saved all you can elsewhere.
- You need it for estate planning.
- You need a forced savings plan because you know you’ll raid a regular investment account.
The honest middle ground
Most people just need a bridge. They need insurance for the next 20 or 30 years while they pay off the house and get the kids through school. For that, term life is almost always the right answer.
Don't get paralyzed by the "invest the difference" debate. Getting term life insurance is way better than having no coverage at all. If you invest the savings, great. If you don't, at least you protected your family during the years it mattered most.
Real families, real numbers
The Chen Family
- Parents are 34, they make $130k together.
- They bought $750,000 of 20-year term each.
- Premium: $65/month combined.
- They invest $300/month in index funds.
- After 20 years at 7%, they should have about $156,000.
Marcus, age 40
- Single dad, makes $85k.
- Bought $500,000, 20-year term.
- Premium: $38/month.
- He invests $200/month.
- After 20 years at 7%, he should have about $104,000.
Both of them are doing what works for them. They have cheap coverage and a growing nest egg.
The Bottom Line
"Buy term and invest the difference" works, but only if you have the discipline to actually do it for decades and accept that the stock market isn't a guarantee. For most families, the main thing is just getting enough insurance to cover the mortgage and the bills. The bills don't stop, and your family needs to be protected.
Get your real numbers from MyMesi
Whether you want term or whole life, MyMesi can help you see your actual rates in about 2 minutes. No pressure, no pushy sales stuff. Just honest numbers so you can decide for yourself.